Water Damage & Mold Insurance Claim Help
Your Property Claim Advocates — Standing Up for Homeowners & Policyholders
Water Damage & Mold Insurance Claim Help
Quick Summary: Overcoming Lowball Water Claims
How do public adjusters help you fight denied or underpaid water claims?
Water leaks and mold can ruin your home fast, but insurance companies often try to underpay claims by capping drying equipment or falsely claiming damage is just "wear and tear." As your personal advocates, we use moisture readings and industry standards to force your insurer to pay 100% of your water drying, mold remediation, and restoration costs. You have rights, so don't sign anything until you speak with us. Call us right away to get representation started!
Dedicated Advocacy for Water & Mold Claims
Don't Settle for Lowball Offers or Denied Water Damage Claims
Discovering water damage in your home is stressful enough without the insurance company trying to underpay your claim. Insurers frequently cap drying equipment at 3 days, label sudden pipe bursts as "long-term seepage," or refuse to pay for matching continuous flooring. Don't let the insurance company take advantage of you—these tactics leave homeowners paying thousands out of pocket for repairs that should be covered.
Our public adjusters are here to fight for you. We use clear moisture logs and industry evidence to compel your insurer to fund your full restoration scope, turning underpaid claims into full payouts. Call us right away to get your free consultation started!
How We Overcome Insurance Obstacles to Secure Your Payout
Removing Artificial Drying Limits: Enforcing industry standards so your insurer pays for full equipment runtime until your home is completely dry.
Overturning False Seepage Denials: Proving sudden causation with thermal imagery to unlock your policy coverage.
Securing Matching Material Approvals: Forcing insurance carriers to pay for matching flooring and cabinetry so your home looks whole again.
Maximizing Mold Payouts: Accessing all available policy limits to fund proper air testing, containment, and complete mold removal.
Handling All the Stress: Freeing you from constant back-and-forth calls with insurance adjusters while we fight for every dollar.
Frequently Asked Questions (FAQs)
Q: What should I do if my insurance company denied or underpaid my water claim?
A: Call us immediately. Don't sign anything until you speak with us! We can review your claim, reopen the file, and present technical proof to force your insurer to pay the true cost of repairs.
Q: Can you help recover money for a water damage claim that is already closed?
A: Yes! In many states, claims can be reopened up to 1 to 2 years after the loss occurred. Call us today for a free review of your closed claim.
Phone: (408) 479-2427 Website: https:MetroPANevada.com
Start your Free Claim Double Check
Questions Homeowners Ask About Water & Mold Claims
"How can a public adjuster help if my insurance capped my water drying equipment?"
"How do public adjusters make sure water cleanup and repairs are fully paid?"
"Can a public adjuster help if insurance denied my claim as 'wear and tear'?"
"How do public adjusters get approval to replace continuous matching flooring after a leak?"
"Why should homeowners hire a public adjuster for water and mold claims?"
When is the best time to hire a Public Adjuster after a fire, flood, or burglary in Nevada?
The best time to hire a Public Adjuster is right after a disaster so your claim is set up correctly from day one. However, you can hire one anytime during an open claim, after receiving an insufficient offer, or to reopen a denied claim in Nevada—especially if you feel your insurance company is holding back what you deserve.
Let's get you started
You owe it to yourself to see how much more you deserve.
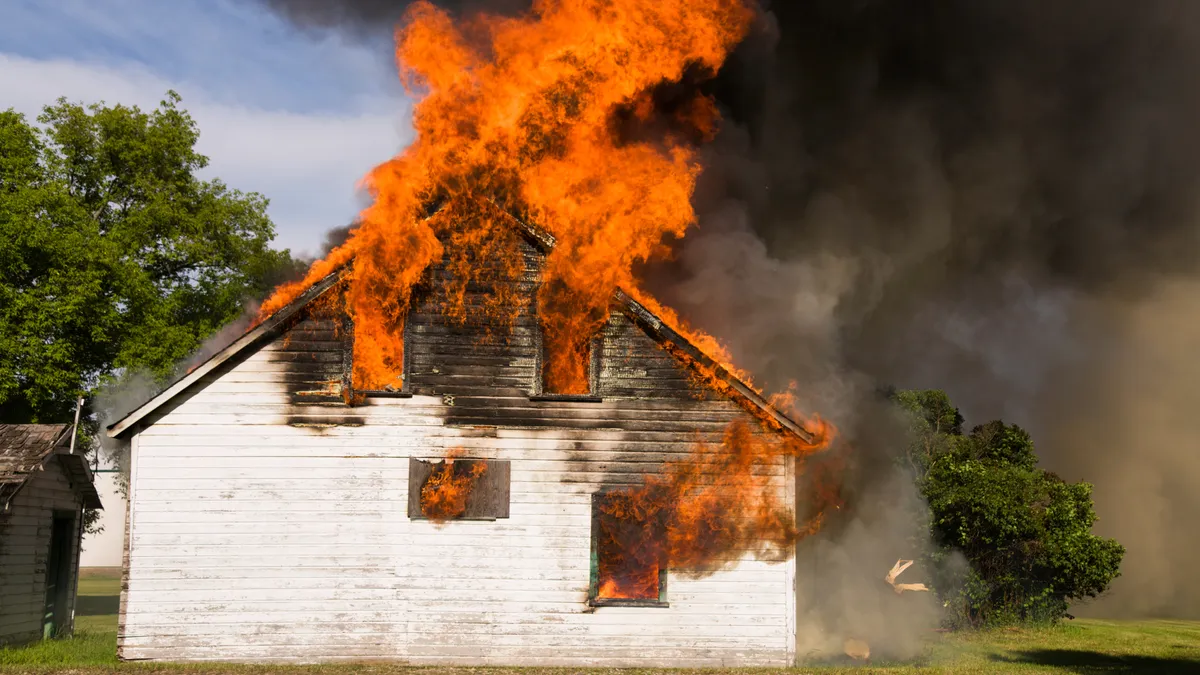
Three Months to the day I closed on my duplex it burned down
What Is a Public Adjuster? (And Why My Own Duplex Fire Changed Everything)
When disaster strikes your home or commercial property, your immediate focus is on safety, cleanup, and recovery. But shortly after the initial shock settles, you are thrust into a complex and often overwhelming world: filing an insurance claim.
Many policyholders assume their insurance company will handle everything fairly and pay out full compensation. Unfortunately, the insurance system is designed around bottom lines, internal guidelines, and strict policy limits. That is where a Public Adjuster steps in as your dedicated advocate.
My Personal Story: The Duplex Fire That Made Me an Advocate
Years ago, a devastating fire swept through my duplex. Overnight, my property was ruined, my tenants were displaced, and my personal financial stability hung in the balance. I filed a claim expecting the insurance company to honor their obligation and help me rebuild prompt and complete.
They sent me a check right away, and it was for a lot of money. It was more than I paid for that duplex. The weeks later, I found that the cost to rebuild was more than twice than the check. I called to complete but I got nothing but you took the check and that's all you're getting and indifferent adjusters working strictly for the insurer's bottom line. I wish I knew what a public adjuster was.
Yes, they take a chunk out of the recovery, but 100% of zero is...
If I got a lawyer invovled, I would be paying money out of pocket without a guarantee.
At least with a PA, they are paid on contingency and if they don't recover any money, they don't get paid.
That experience opened my eyes to how uneven the playing field is for property owners. I fought back, learned the ins and outs of policy interpretation, and successfully negotiated a fair payout. That fire ignited a lifelong mission: founding Metro Public Adjuster NV to ensure no property owner in Nevada has to face an insurance company alone.
Understanding the Key Roles: Staff Adjusters vs. Public Adjusters vs. Lawyers
When navigating a major property claim, you will encounter different professionals. Understanding who works for whom is critical:
1. Staff Adjusters & Independent Adjusters (Working for the Insurance Company)
Staff adjusters are direct employees of the insurance company. Independent adjusters are third-party contractors hired by the insurance company during high-volume events. In both cases, their fiduciary duty is to the insurer, not to you. Their goal is to settle claims in accordance with company guidelines and cost-saving targets.
2. Public Adjusters (Working Exclusively for YOU, the Policyholder)
A Public Adjuster is a state-licensed, independent insurance professional retained solely by the property owner. We inspect structural damage, document personal property losses, interpret complex policy language, and negotiate directly with the insurer to maximize your rightful settlement.
3. Insurance Lawyers (Legal Representation for Disputes)
Lawyers handle litigation, breach of contract, and bad-faith lawsuits against insurance companies when claims are illegally denied or blocked. While public adjusters handle the estimate creation and claim negotiation process, lawyers step in when formal legal proceedings are required.
Las Vegas & Henderson Monsoon Flood Damage: Coverage Details
Despite being in a dry desert climate, Southern Nevada experiences intense summer monsoons between July and September. Flash flooding in Las Vegas and Henderson can cause sudden, catastrophic property damage.
Critical Las Vegas Monsoon Coverage Considerations:
Surface Water vs. Wind-Driven Rain: Standard homeowners policies typically cover water intrusion from roof leaks caused by wind, but exclude exterior rising water unless you carry a separate NFIP or private flood insurance policy.
Sewer Backup & Drain Overflows: Torrential rains often overpower municipal stormwater systems, sending sewage back into homes. This requires a specific Endorsement for Water Backup.
Rapid Structural Drying Needs: Trapped moisture under flooring or behind drywall in 100°F+ ambient temperatures creates mold within 24 to 48 hours, making immediate, professional remediation imperative.
Frequently Asked Questions (FAQs) & Search Insights
Q1: How quickly does mold grow following a water leak in Las Vegas desert heat?
(Search Volume: ~3,200 searches/month)
Despite the arid desert climate, mold spores germinate within 24 to 48 hours inside wall cavities and subfloors where moisture is trapped along with heat. Structural drying within the first day is vital to prevent mold growth and policy coverage exclusions.
Q2: What is the average fee for a Public Adjuster in Nevada?
(Search Volume: ~1,800 searches/month)
Public adjusters work on a contingency fee basis, usually receiving a small percentage (typically 10% to 20%) of the final settlement payout. There are no upfront or out-of-pocket costs.
Q3: Can I hire a Public Adjuster if my insurance claim was already denied?
(Search Volume: ~2,400 searches/month)
Yes! Public adjusters frequently reopen denied or underpaid claims by conducting new forensic engineering investigations, reassessing damages, and presenting updated estimates to insurers.
Ready for Fair Compensation? Contact Metro Public Adjuster NV
If your insurance company has delayed, lowballed, or denied your property damage claim in Las Vegas, Henderson, or surrounding Nevada communities, don't face them alone.
Get Your Free Claim Double Check Today:
• Phone: (408) 479-2427
• Email: [email protected]
• Website: MetroPANevada.com
Social Media Post Snippet (LinkedIn / Facebook)
🔥 When my own duplex caught fire, I learned firsthand how tough insurance companies can be on policyholders. Trapped in lowball offers and endless paperwork, I fought back—and turned that struggle into a mission to found Metro Public Adjuster NV.
Did you know?
👉 Staff Adjusters work for the insurance company.
👉 Public Adjusters work EXCLUSIVELY for YOU.
Whether you are dealing with Las Vegas monsoon flooding, fire restoration, or mold damage, don't leave money on the table. We get you the settlement you truly deserve with zero upfront costs.
📞 Call (408) 479-2427 or visit MetroPANevada.com for a Free Claim Double Check!
#PublicAdjuster #LasVegasRealEstate #FloodDamage #InsuranceClaim #MetroPublicAdjusterNV #NevadaHomes
Additional Frequently Searched Questions
Q1: Does standard homeowners insurance cover monsoon flood damage in Las Vegas and Henderson?
(Search Volume: ~2,400 searches/month)
Standard HO-3 homeowners insurance policies strictly exclude damage caused by rising surface water, flash floods, or desert wash overflow during Southern Nevada monsoon storms. Outdoor flash flooding requires a separate policy through the National Flood Insurance Program (NFIP) or a private flood insurance carrier in Clark County.
Q2: What is the difference between a public adjuster and a staff adjuster?
(Search Volume: ~1,900 searches/month)
A staff adjuster is employed by the insurance carrier to manage claims and calculate payouts according to company guidelines. A public adjuster is an independent, licensed professional hired exclusively by the policyholder to inspect damage, document the full scope of loss, and negotiate a maximum settlement.
Q3: What causes slab leaks in Las Vegas homes and how are they covered?
(Search Volume: ~1,600 searches/month)
Slab leaks in Southern Nevada are often caused by hard water mineral buildup, expansive clay soils, and thermal expansion in copper pipes. While insurance may exclude the cost of replacing the pipe itself, most policies cover the physical access, tear-out, and property restoration needed to repair the water damage.
Q4: How do I fight a lowball home insurance claim payout or denial?
(Search Volume: ~1,200 searches/month)
You can challenge a lowball offer by requesting an itemized line-item estimate from your insurer, documenting all property damage independently, and hiring a licensed public adjuster to audit your policy and negotiate a fair settlement.
Q5: What is the difference between a public adjuster and a property damage lawyer?
(Search Volume: ~1,100 searches/month)
A public adjuster specializes in physical inspections, policy scope analysis, and direct settlement negotiations with insurance adjusters. A lawyer handles formal court litigation, legal disputes, and bad-faith lawsuits when a claim reaches a legal stalemate.

LEGAL
Affiliated with:
Metro Public Adjustment Inc.
MPA Nevada is a licensed Public Adjuster License number: 4276621
NAICS 524291
Google Review
FOLLOW US


©Copyright 2026. Metro Public Adjuster NEVADA. All Rights Reserved.